ARTICLE
Complete Guide to Insurance Comparison in Hong Kong
12-min read
Updated on 2026-4-9
Author: AIA Content Editorial Team
Why Is Insurance Comparison Important Before Purchasing Insurance?
Core Indicator 1: How Claim Structure Relates to Coverage Scope
Understanding "Full Coverage" vs "Sub-limits" in Medical Insurance
Comparing Disease Coverage and Multiple Claims in Critical Illness Protection
Core Indicator 2: Savings Features and Long-term Wealth Growth Potential
- Return structure (guaranteed vs non-guaranteed): You are advised to clarify the proportion of guaranteed cash value versus non-guaranteed returns. In general, products with a higher guaranteed portion may provide a clearer and more stable indication of policy value. According to the Hong Kong Insurance Authority, non-guaranteed returns (often referred to as bonuses) are not guaranteed payouts. Insurers determine bonus levels based on factors such as investment strategy, claims experience, and operating expenses². While products with a higher non-guaranteed portion may offer greater long-term growth potential, their policy value may also be more susceptible to fluctuations.
- Product positioning and policy term: different product positioning (conservative vs growth-oriented) will affect the guaranteed/non-guaranteed mix. You should also compare policy terms (e.g., 3 years, 5 years, and up to 30 years) to evaluate expected returns and liquidity.
Core Indicator 3: Tax Benefits and Regulatory Compliance#
Using Tax Deduction Caps to Optimise Financial Planning
- Voluntary Health Insurance Scheme (VHIS): VHIS offers standardised medical protection, and the maximum tax-deductible premium is HKD 8,000 per insured person per year³. Click to view eligible VHIS plans.
- Qualifying Deferred Annuity Policy (QDAP): QDAP helps individuals plan early for retirement. Each taxpayer can enjoy a tax deduction cap of up to HKD 60,000 per year⁴ (combined with tax-deductible MPF voluntary contributions). If you want to build a stable retirement income stream, you may consider selecting an appropriate deferred annuity plan.
Core Indicator 4: Service Quality and Claims Support
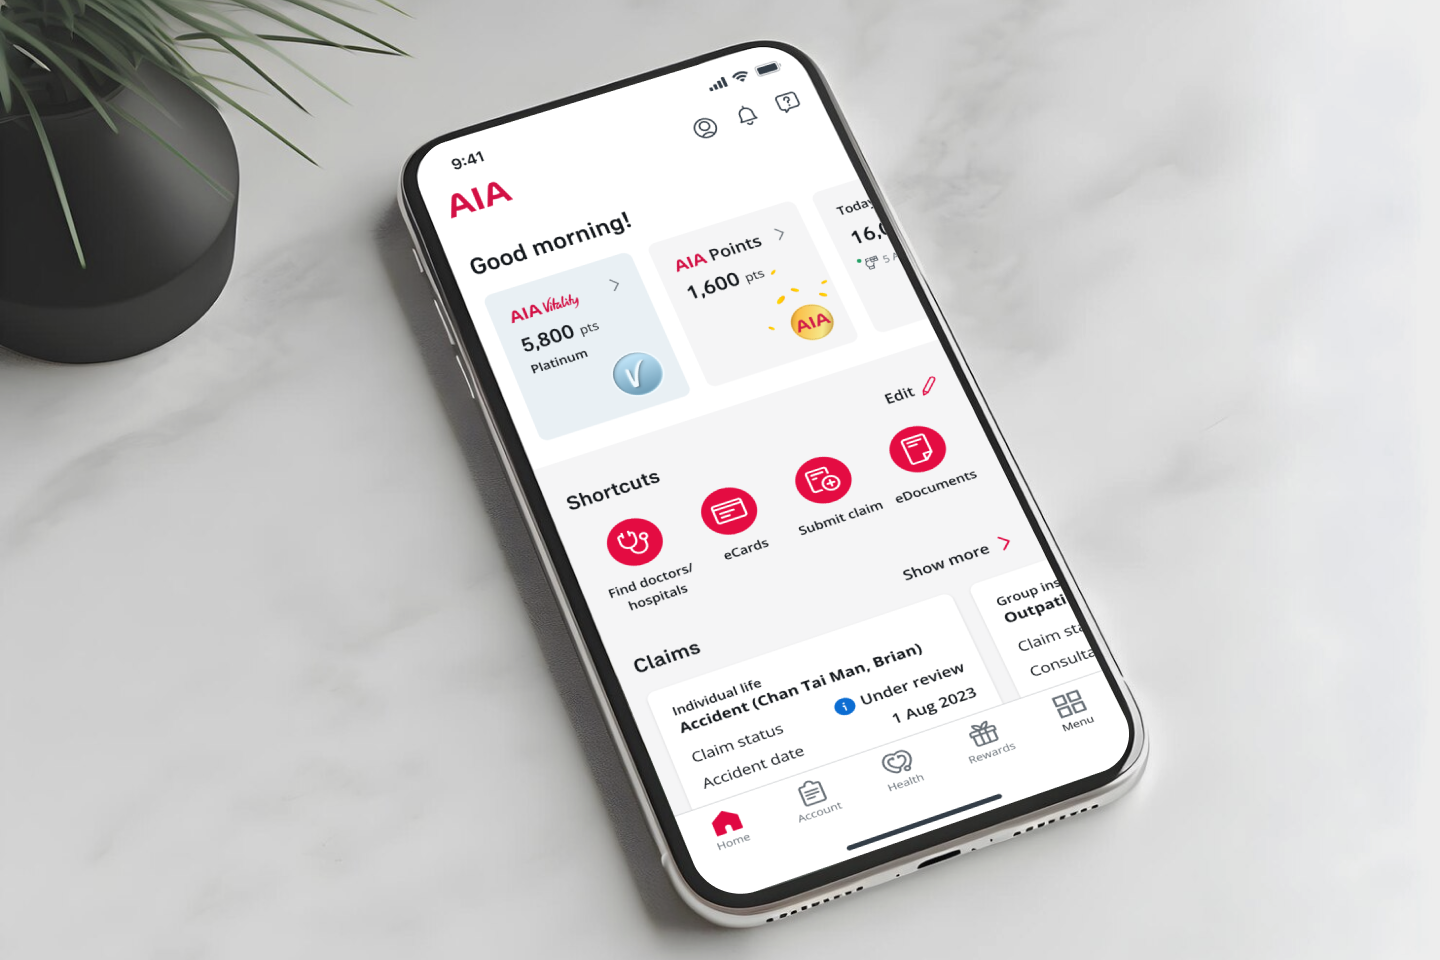
Evaluating Digital Claims Efficiency and Advisor Professionalism
Key Factors to Consider When Comparing Insurance Plans
Pre-existing Conditions, Exclusions, and Waiting Periods
- Exclusions5: Exclusions refer to situations not covered by the policy. In addition to common exclusions such as pre-existing conditions, some plans may exclude certain high-risk activities or specific congenital conditions.
- Waiting Period5: Many policies do not cover illnesses that occur during the initial period (e.g., the first 60–90 days) after the policy becomes effective.
- In addition, definitions of "accident" or certain illnesses may differ slightly among insurers, and these small differences can significantly affect claim outcomes.