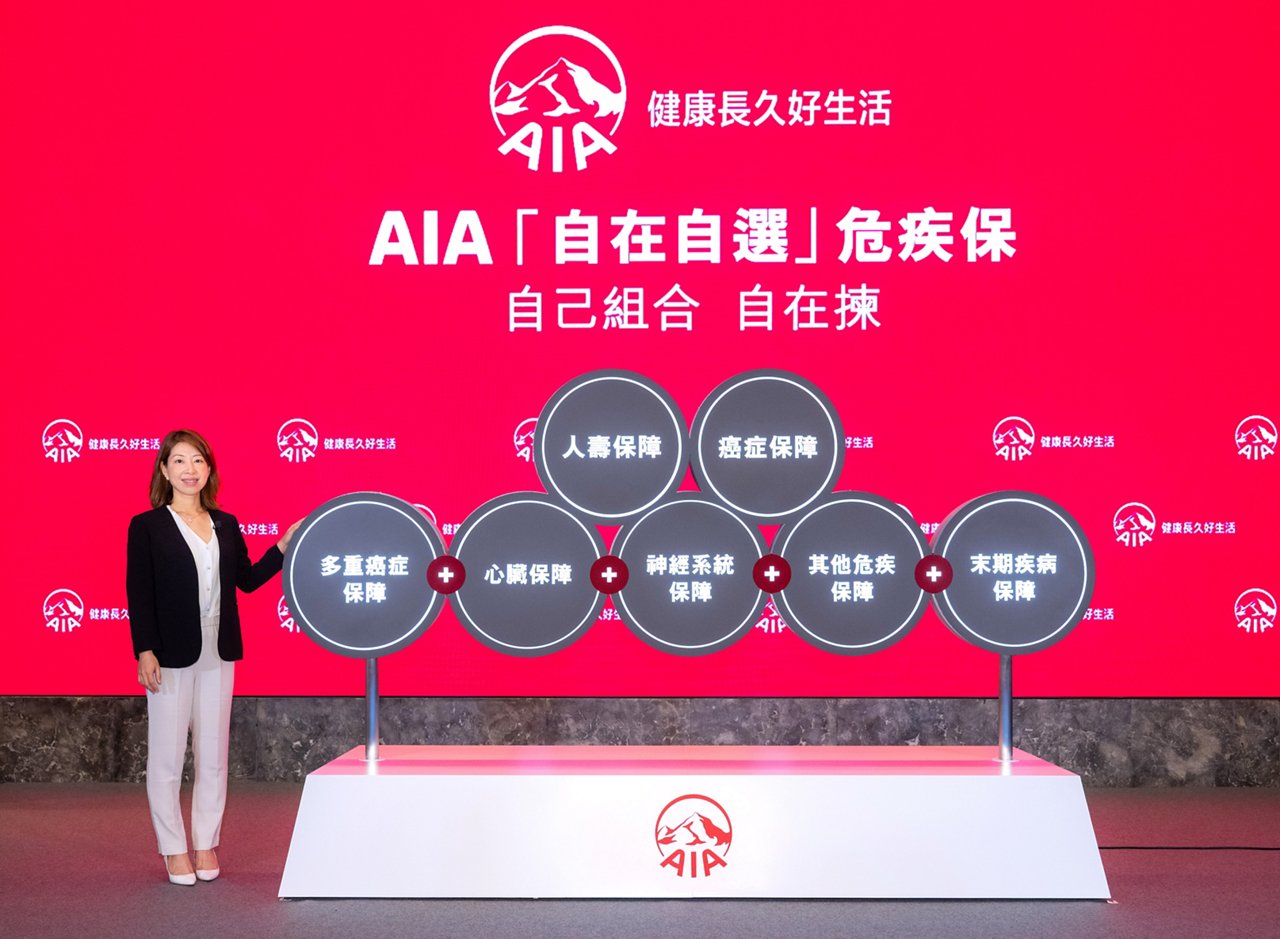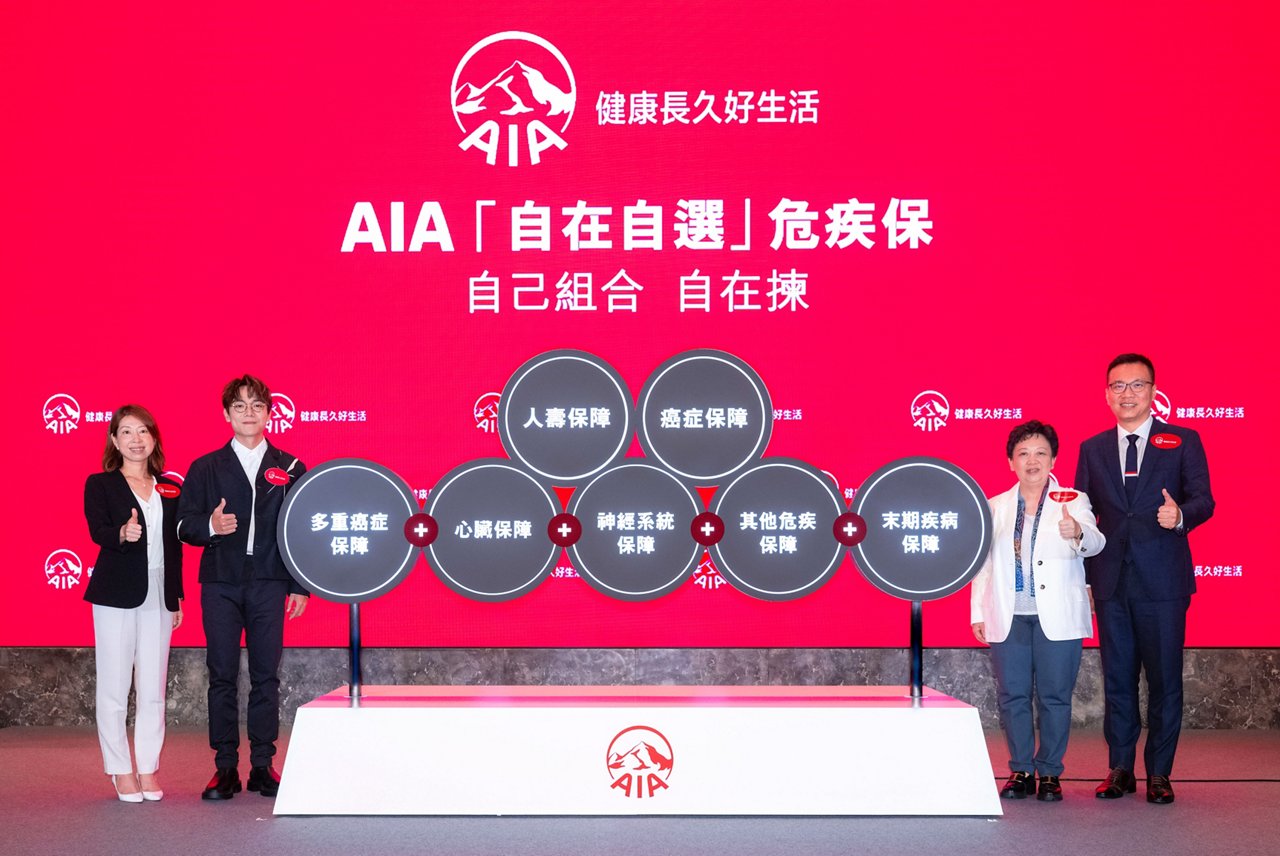






AIA Hong Kong today announced that it will soon launch "AIA Assemble", a first-in-market1, customisable critical illness plan that sets a new industry standard by enabling customers to tailor their critical illness protection and sum assured and thus enjoy higher levels of flexibility and freedom. In addition to compulsory Life Cover and Cancer Cover, AIA Assemble offers customers the freedom to select critical illness covers2 for multiple cancer, cardiovascular, neurological and other illnesses. Moreover, Multiple Cancer Cover offers up to five additional cancer claims. Customers may tailor their sum assured for each critical illness cover based on individual needs and budget, up to a maximum of three times the Initial Sum Assured of the Life Cover3. The innovative new product has been designed as a response to the findings of a survey4 recently carried out by AIA Hong Kong on customers' critical illness protection needs and pain points.
Assuming the inclusion of all optional critical illness covers, the combined sum assured of the covers can be up to 25 times the Initial Sum Assured of the Life Cover. Critical illness covers are also independent of each other, meaning claims for any specific critical illness cover will not affect the protection of other critical illness covers. During the promotional period, up to a four-month premium refund5 and one dose of the HPV vaccine5 will be offered upon successful application.
AIA Hong Kong recently conducted a customer survey4 that aimed to identify trends in critical illness protection needs and customers' pain points. Below are some of the key findings that informed the design of the new product:
- Nearly half of respondents between the ages of 18 and 29 said they do not feel an urgent need to purchase critical illness insurance, the highest percentage among all customer segments. The younger the respondents were, the less they felt they needed insurance.
- Close to 60% of respondents aged between 18 and 29 indicated that they are most concerned about the premium when purchasing critical illness protection products. This percentage was the highest among all customer segments.
- Nearly 30% of respondents who already had a critical illness protection plan still felt that their protection was not sufficient. The average perceived gap was around HK$1.84 million.
Ms Alice Liang, Chief Proposition Officer of AIA Hong Kong & Macau, said, "We are seeing a trend of increasing incidence of critical illnesses at younger ages, but young customers may easily lose sight of the importance of having critical illness protection. According to our survey, about 70% of respondents indicated that if they could tailor-make their own critical illness protection plan, they would be more inclined to buy insurance. This view was most prevalent in young respondents between the ages of 18 and 29.
"At the same time, awareness among customers who have bought critical illness protection plans is growing, and with it the desire to find the right solution to fill their protection gaps," Ms Liang continued. "We understand that customers have different critical illness protection needs and budgetary considerations, and that many wish to have more flexibility when it comes to making choices about insurance cover. AIA Assemble, the first product of its kind in the market, offers customers unprecedented freedom to customise their critical illness cover by enabling them to build their own protection plans. AIA Assemble is particularly well suited for younger customers who value flexibility, as well as those who have already bought critical illness plans but wish to strengthen specific aspects of their personal protection in order to live Healthier, Longer, Better Lives."
AIA Assemble is a participating insurance plan that provides critical illness and life protection for the insured up to the age of 1006 as well as the opportunity for wealth accumulation. The key features of the plan include:
- First-in-market1 customisation of critical illness cover2: Customers may add four optional covers, including multiple cancer, as well as cardiovascular, neurological and other illnesses, to compulsory Life Cover and Cancer Cover. Customers who choose all covers7 will automatically be offered an exclusive cover for Terminal Illness and Loss of Independent Existence8, totalling seven covers. Customers' underwriting requirements may differ according to the selected covers.
- Customisation of sum assured of specific critical illness cover: AIA Assemble customers may also enjoy the freedom to set the sum assured of a specific critical illness cover up to 300% of the Initial Sum Assured of the Life Cover3. The combined sum assured of all critical illness covers may be up to 25 times the Initial Sum Assured of the Life Cover9.
- Up to five additional claims for optional Multiple Cancer Cover: Customers who opt for Multiple Cancer Cover may make up to five additional claims for a new cancer or the continuation, metastasis or recurrence of a previous cancer. Each cancer claim must fulfil the three-year waiting period.
- Premiums and claims of critical illness covers are calculated independently10: A claim for one critical illness cover will not affect the protection offered by other critical illness covers. Even if a certain benefit for a critical illness cover has been paid out, a customer may still make claims for other critical illness covers. When the benefit amount for a cover has been fully paid out and the current sum assured of the cover has been reduced to zero, the customer will no longer be required to pay the premium for that cover11.